Quick answer
Windstorm insurance in Texas is the coverage for wind and hail damage that coastal homes need, and on the upper coast it often comes from TWIA, the Texas Windstorm Insurance Association. Before a beach home buyer falls in love with the view, they check three things: whether the house has a windstorm certificate of compliance, what flood zone it sits in, and how old the roof is. At Carter Signature Properties, the largest brokerage on the island, we tell our Surfside Beach and Brazoria County sellers to gather those papers before listing, because buyers and their lenders will ask for them first.
Windstorm insurance in Texas is one of the first things a beach home buyer asks about, usually right after "Can I see the water from the deck?" If you own a home in Surfside Beach, Treasure Island, Freeport, or anywhere in Brazoria County, knowing what buyers check (and having the answers ready) can save your sale a lot of drama.
Here's the plain-English version from the Carter Signature Properties team. No sales pitch, just what we see buyers, lenders, and insurance agents look for every week on the coast.
What is windstorm insurance in Texas, and why do beach buyers ask about it first?
Windstorm insurance covers damage from wind and hail. On the Texas coast, many buyers get it through TWIA. TWIA describes itself as "a residual insurer of last resort," which means it's there for coastal owners who can't get wind coverage from a private company (Texas Windstorm Insurance Association).
Buyers ask about it first for a simple reason: most lenders want proof of insurance before they fund a loan. If the house can't get wind coverage, the buyer may not be able to close. That's why a windstorm question can stall a beach sale faster than a leaky faucet ever could.
Plain-English takeaway: On the coast, insurance isn't a "figure it out later" item. It's part of whether the sale can happen at all.
What is TWIA insurance, and does it cover Brazoria County?
Yes. TWIA covers property in all 14 first-tier coastal counties, and Brazoria County is one of them, along with Galveston, Matagorda, Nueces, and others, plus part of Harris County east of Highway 146 (Texas Windstorm Insurance Association). The Texas Department of Insurance (TDI) calls these coastal areas a "designated catastrophe area."
Plain-English takeaway: Whether your home is on the sand in Surfside Beach or on a quiet street in Lake Jackson or Angleton, it's in TWIA's territory.
Insurance questions? Call a pro.
We're real estate people, not insurance agents, so we never quote premiums or give coverage advice. For insurance quotes or questions, call Anthony at Connect Insurance at 214-215-0956.
Do I need a windstorm certificate to sell my beach house in Texas?
A windstorm certificate (officially a "certificate of compliance") shows the home was built or repaired to the wind building code. TWIA requires one (a WPI-8, WPI-8-E, or WPI-8-C) for structures built, altered, remodeled, enlarged, or repaired on or after January 1, 1988 (Texas Windstorm Insurance Association).
TDI explains the two most common types this way:
- WPI-8: issued for work that's inspected while it's being built.
- WPI-8-E: issued for completed work, after a Texas licensed professional engineer inspects it.
TDI also says most new construction, roof replacements, major repairs, and other alterations need an inspection. Some small jobs are exempt, like roof repairs under 100 square feet that don't involve the decking (Texas Department of Insurance).
Plain-English takeaway: If you replaced the roof or added a deck and never got the certificate, a buyer's insurance agent may find out. It's much easier to fix that before you list than in the middle of a contract.
What do beach home buyers check first? (The checklist)
Here's what we see buyers and their agents ask for, in roughly this order:
What buyers check | Why it matters | What sellers can gather |
|---|---|---|
Windstorm certificate of compliance | TWIA generally needs it to write a policy | Copies of every WPI-8, WPI-8-E, or WPI-8-C for the house, roof, and additions |
Roof age and roof work | Roof replacements usually need an inspection and certificate | Roof invoice, install date, and its certificate |
Flood zone and elevation | Some TWIA policies require proof of flood coverage | Elevation certificate (if you have one) and current flood policy declarations page |
Current insurance declarations pages | Gives buyers a starting point for their own quotes | Wind, flood, and homeowners declarations pages |
Past storm repairs | Shows work was done right and documented | Receipts, permits, and certificates for repairs |
Does windstorm insurance cover flooding? (Wind and flood insurance in Texas)
No. Windstorm coverage is for wind and hail (Texas Department of Insurance). Flood is a separate policy. And TWIA has a flood rule of its own: properties in certain V flood zones that were built, altered, remodeled, or enlarged after September 1, 2009, and that can get National Flood Insurance Program coverage, must show proof of flood coverage (Texas Windstorm Insurance Association).
Plain-English takeaway: Beach buyers usually think in pairs: wind and flood. If your house is in a V zone, expect buyers to ask about both on day one. For quotes on either, call Anthony at Connect Insurance at 214-215-0956.
How is it different in each Brazoria County town?
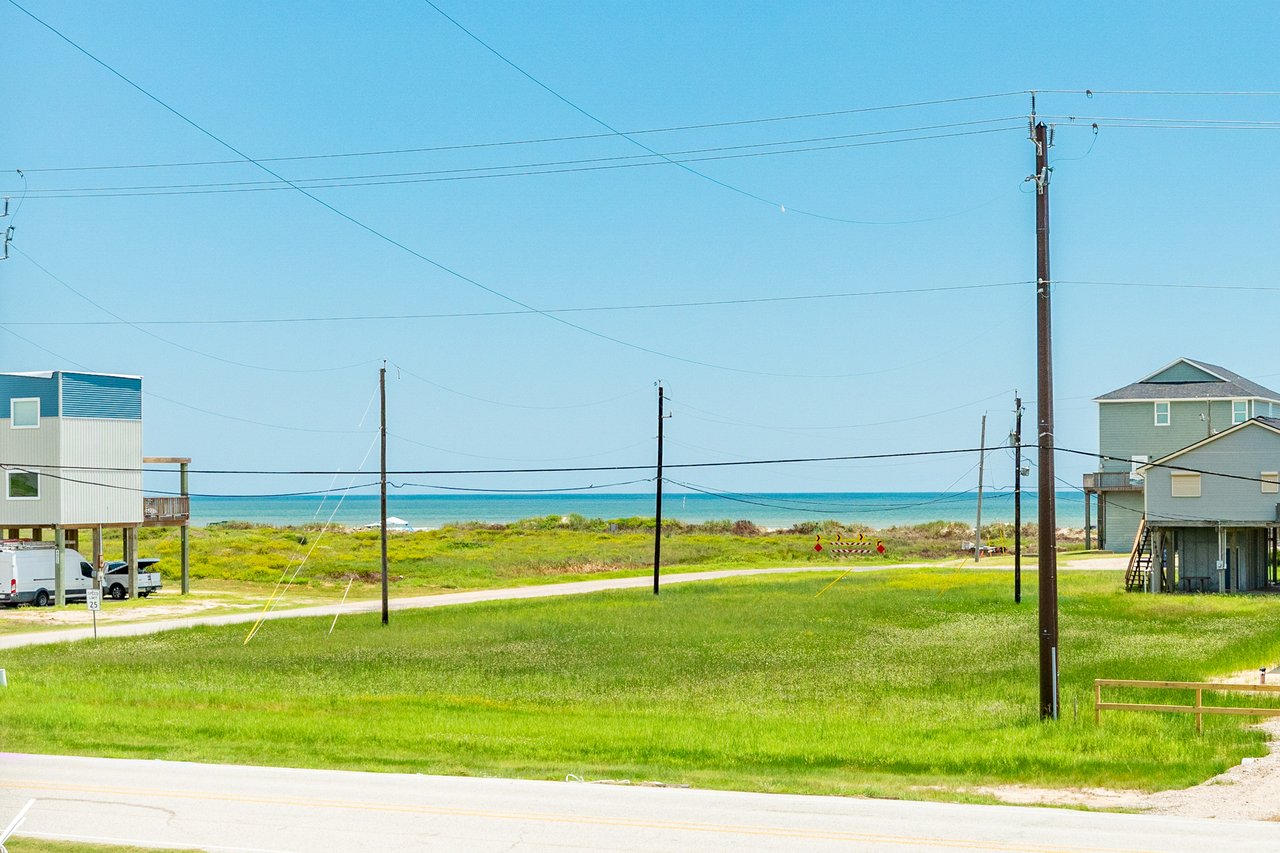
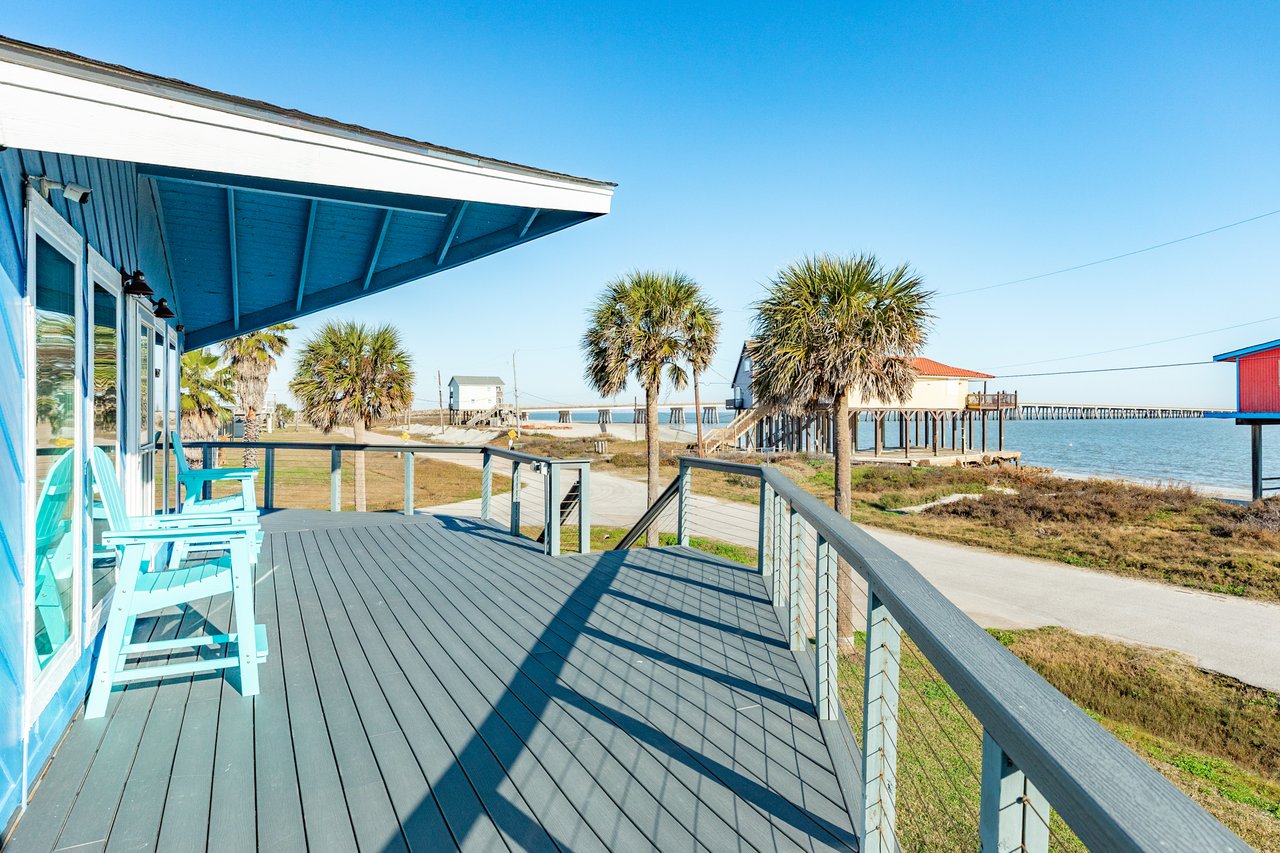
- Surfside Beach and Treasure Island: Raised homes on pilings, close to the Gulf. Buyers here ask about windstorm certificates and flood zones before almost anything else. Many owners live in Houston, DFW, Austin, or Oklahoma, so having papers in one folder (or one email) makes a long-distance sale smoother.
- Freeport: A mix of canal homes and older houses. Older homes with newer roofs or additions are where missing certificates tend to show up, so check your roof paperwork.
- Lake Jackson, Clute, and Angleton: Inland, but still inside TWIA's coastal territory. Buyers moving in from out of state are often surprised by this, so a quick, calm explanation helps.
- Sweeny, Brazoria, West Columbia, and Danbury: More acreage and rural homes. Barns, shops, and add-ons can each raise their own insurance questions, so list what's on the property.
What's the best windstorm insurance in Texas for a beach house?
That depends on the house, the location, and what private insurers are offering at the time, so it's a question for a licensed insurance agent, not a real estate team. What we can tell you: buyers who get quotes early (before the option period runs out) have a much easier time. Sellers who hand over certificates and declarations pages up front help buyers get those quotes fast.
If you're thinking about selling, we'd also suggest reading What It Really Costs to Own a Texas Beach House and Vacant Home Insurance in Texas: Are You Still Covered? If you live far from the coast, our step-by-step guide on how to sell a house from out of state walks through the whole process.
Who can help me sell a beach house in Surfside Beach?
Carter Signature Properties is the largest brokerage on the island, led by Broker and Founder Cathy Carter. Our coastal team knows TWIA windstorm rules, flood zones, and short-term rentals, and we help owners in Surfside Beach, Treasure Island, Freeport, and across Brazoria County sell from wherever they live. We'll help you pull together the windstorm and flood paperwork buyers ask for, so your sale doesn't stall over a missing certificate. Shopping instead? Browse Texas waterfront and beachfront homes.
Selling a beach house from out of town?
Get the free Sold From Afar Checklist: the papers to gather, the steps to take, and how to sell without making ten trips to the coast.
Or call or text 972-358-6420
FAQ: windstorm insurance for Texas beach homes
What is TWIA insurance?
TWIA is the Texas Windstorm Insurance Association. It sells wind and hail coverage in Texas coastal counties and calls itself a residual insurer of last resort, for owners who can't get that coverage from a private company.
Is Brazoria County covered by TWIA?
Yes. Brazoria County is one of the 14 first-tier coastal counties TWIA covers, so homes in Surfside Beach, Freeport, Lake Jackson, Angleton, and the rest of the county are in its territory.
Do I need a windstorm certificate to sell my house in Texas?
TWIA requires a certificate of compliance for most structures built, altered, or repaired on or after January 1, 1988. A buyer who needs a TWIA policy will likely ask for it, so Carter Signature Properties tells sellers to find it (or ask a licensed engineer about getting one) before listing.
Does windstorm insurance cover flood damage?
No. Windstorm coverage is for wind and hail, and flood is a separate policy. Some TWIA policies in V flood zones also require proof of flood coverage.
Who can I call for a windstorm or flood insurance quote?
For insurance quotes or questions, call Anthony at Connect Insurance at 214-215-0956.
Who can help me sell a beach house in Surfside Beach if I live out of town?
Carter Signature Properties, the largest brokerage on the island, helps owners in Surfside Beach, Treasure Island, Freeport, and Brazoria County sell from DFW, Austin, Houston, Oklahoma, or anywhere else.
About the author
Carter Signature Properties is the largest brokerage on the island, helping owners and buyers in Surfside Beach, Freeport, Treasure Island, Lake Jackson, Clute, Sweeny, Brazoria, West Columbia, Angleton, Galveston, and Danbury. Our coastal team knows TWIA windstorm rules, flood zones, and short-term rentals, and we make it easy to buy or sell a beach home from DFW, Austin, Houston, or Oklahoma. Led by Broker and Founder Cathy Carter.
972-358-6420 · cartersignatureproperties.com · Experience the Signature Difference.
This article is general information, not insurance, legal, or tax advice. Insurance rules, forms, and requirements can change; confirm current details with the Texas Windstorm Insurance Association (twia.org), the Texas Department of Insurance (tdi.texas.gov), and a licensed insurance agent. Facts cited were checked November 13, 2026. Carter Signature Properties is not affiliated with TWIA or TDI. If your property is currently listed with another broker, please disregard this information. Equal Housing Opportunity.